


Payroll processing in India is the systematic process of calculating employee salaries, applying deductions, managing statutory contributions, processing taxes, and paying employees accurately and on time. A structured payroll process helps employers maintain compliance while reducing salary errors and administrative work.
From attendance and leave records to PF, ESI, Professional Tax, TDS, reimbursements, and payslips, several components must be reviewed before payroll is finalized. Employers also need to maintain accurate employee data and meet applicable statutory payment and filing requirements.
For growing businesses, payroll processing can become increasingly complex as employee numbers, locations, salary structures, and compliance requirements increase. Understanding each stage of payroll helps employers build an accurate, transparent, and compliant payroll management system.
What Is Payroll Processing in India?
Payroll processing in India refers to the complete process of calculating and paying employee salaries after considering earnings, attendance, leave, deductions, taxes, statutory contributions, reimbursements, and other payroll-related adjustments.
In simple terms, payroll processing determines how much an employee should receive and how much the employer must deduct, contribute, report, or deposit on the employee’s behalf.
A general payroll process starts with collecting employee and attendance information and ends with salary disbursement, payslip generation, statutory payments, and payroll record maintenance.
Why Is Payroll Processing Important?
Payroll is more than simply transferring salaries to employees. An effective payroll process helps employers:
- Pay employees accurately and on time.
- Calculate gross salary, deductions, and net salary correctly.
- Manage PF, ESI, Professional Tax, and other applicable statutory deductions.
- Calculate and deduct salary TDS.
- Maintain payroll records for audits and reporting.
- Generate accurate payslips.
- Reduce payroll errors and disputes.
- Improve employee trust and transparency.
- Meet applicable payroll compliance requirements.
- Maintain a consistent salary processing cycle.
Because payroll involves employee compensation and statutory obligations, even a small calculation or data error can affect employees and create compliance issues for employers.
How Does Payroll Processing Work in India?
Payroll processing generally follows a monthly cycle, although the exact frequency and internal workflow may differ between organizations.
The basic payroll workflow can be represented as:
Employee Data → Attendance & Leave → Earnings → Gross Salary → Statutory Deductions → TDS → Other Deductions → Net Salary → Approval → Salary Disbursement → Payslip → Compliance & Records
The process normally begins by collecting employee information and monthly attendance data. HR or payroll teams then calculate salary components, overtime, incentives, bonuses, reimbursements, and applicable deductions.
After the payroll calculation is reviewed and approved, the organization processes salary payments through the applicable banking system and generates payslips.
The payroll team must then complete applicable statutory payments, filings, reconciliations, and record-keeping activities.
What Information Is Required for Payroll Processing?
Common payroll inputs include:
- Employee name and employee ID
- Date of joining
- PAN and other required tax information
- Bank account details
- Salary structure
- Basic salary
- Allowances
- Attendance records
- Leave records
- Overtime
- Incentives and bonuses
- Reimbursements
- Loan or salary advance deductions
- PF applicability
- ESI applicability
- Professional Tax applicability
- TDS information
- Investment or tax-related declarations and supporting information, where applicable
Accurate payroll starts with accurate data. Therefore, employers should establish a defined payroll cut-off date for receiving attendance, leave, reimbursement, and other payroll inputs.
What Are the 8 Steps in the Payroll Processing Cycle?
A standard payroll processing cycle can be divided into 8 practical steps.
Step 1: Collect and Verify Employee Payroll Data
The first step is to collect all information required to calculate salaries.
This includes employee master data, salary structures, attendance, leave, overtime, incentives, reimbursements, deductions, and changes in employment status.
Payroll teams should verify important changes such as:
- New employees
- Resignations
- Promotions
- Salary revisions
- Transfers
- Changes in bank details
- Changes in tax declarations
- Changes in statutory applicability
Incorrect employee data can lead to incorrect salary calculations, so data validation should happen before payroll is processed.
Step 2: Finalize Attendance, Leave, and Overtime
Attendance and leave directly affect payroll.
The payroll team should finalize:
- Present days
- Paid leave
- Unpaid leave
- Holidays
- Weekly offs
- Overtime
- Late attendance, where applicable
- Shift-related adjustments
- Loss of Pay (LOP)
For employees paid on a monthly basis, unauthorized or unpaid absence may result in a salary deduction depending on the organization’s payroll policy.
Step 3: Calculate Gross Salary and Earnings
The next step is to calculate the employee’s earnings for the payroll period.
Salary earnings may include:
- Basic salary
- House Rent Allowance (HRA)
- Special allowance
- Conveyance or transport-related allowance
- Performance incentives
- Overtime
- Bonus
- Commission
- Other applicable allowances
- Reimbursements, depending on payroll treatment
The exact salary structure differs by organization, employee, role, and employment agreement.
Step 4: Calculate Statutory Deductions
Once earnings are calculated, applicable statutory deductions must be determined.
Common payroll deductions include:
- Employee PF contribution
- Employee ESI contribution, where applicable
- Professional Tax, where applicable
- Salary TDS
- Other legally permitted deductions
The applicability and calculation of these deductions depend on the employee, establishment, salary components, location, and applicable law.
Step 5: Calculate TDS on Salary
Employers must calculate salary TDS according to the applicable income-tax provisions.
For salary paid from April 2026 onward, the Income Tax Department states that salary TDS is governed by the Income Tax Act, 2025, with the salary withholding provision under Section 392(1). The payroll system therefore needs to reflect the new tax-year framework and applicable section references.
Payroll teams generally consider projected taxable salary, applicable exemptions/deductions, tax regime, and employee declarations while determining TDS.
Step 6: Calculate Net Salary
After calculating earnings and deductions, payroll determines the employee’s net salary.
The basic formula is:
Net Salary = Gross Earnings − Employee Deductions − TDS − Other Applicable Deductions
Net salary is the amount that the employee receives after applicable deductions.
Step 7: Review, Approve, and Process Payroll
Before salary disbursement, payroll should be reviewed for errors.
Important checks include:
- Total payroll cost
- Employee count
- New joiners
- Exits
- Salary revisions
- LOP deductions
- Overtime
- Incentives
- PF and ESI values
- TDS
- Professional Tax
- Bank account changes
- Unusual salary variations
The payroll should ideally be approved by an authorized person before salary files or payment instructions are released.
Step 8: Disburse Salaries and Generate Payslips
Once payroll is approved, salaries are transferred to employees through the organization’s salary payment process.
After processing, employees should receive payslips containing relevant salary information, such as:
- Earnings
- Deductions
- Net salary
- Employee details
- Employer details
- Applicable statutory deductions
The payroll team should also complete applicable statutory payments, filings, reconciliations, and record-keeping.
What Salary Components Are Included in Payroll Processing?
Salary components vary between organizations, but a general Indian salary structure may include several earnings and deductions.
Common Earnings
| Salary Component | Description |
| Basic Salary | Core component of salary and often used as a basis for certain statutory calculations |
| HRA | Allowance generally provided toward housing expenses |
| Special Allowance | Flexible salary component used in many salary structures |
| Conveyance/Transport Allowance | May be provided according to organizational policy |
| Bonus | Additional payment based on eligibility or company policy |
| Incentives | Performance or target-based earnings |
| Overtime | Payment for eligible additional working hours |
| Reimbursements | Eligible business-related expenses reimbursed by the employer |
Common Deductions
| Deduction | Purpose |
| PF | Retirement/social-security contribution where applicable |
| ESI | Social security contribution for eligible employees |
| Professional Tax | State-level employment tax where applicable |
| TDS | Tax deducted from salary according to applicable income-tax provisions |
| LOP | Salary adjustment for applicable unpaid absence |
| Loan/Advance | Recovery of authorized employee loans or salary advances |
Employers should not assume that every salary component is treated identically for every statutory calculation. The definition of wages, exemptions, thresholds, and applicability should be checked under the relevant legislation and current rules.
How Is Salary Calculated in India?
Salary calculation generally starts with determining the employee’s applicable earnings for the payroll period and then subtracting authorized deductions.
A simplified calculation is:
Gross Salary = Basic Salary + Allowances + Incentives + Overtime + Other Earnings
Then:
Net Salary = Gross Salary − Statutory Deductions − TDS − Other Applicable Deductions
Example
Suppose an employee has:
- Basic Salary: ₹30,000
- HRA: ₹12,000
- Special Allowance: ₹8,000
- Other Earnings: ₹5,000
The gross salary would be:
₹30,000 + ₹12,000 + ₹8,000 + ₹5,000 = ₹55,000
The employee’s applicable deductions would then be calculated based on the relevant rules and the employee’s circumstances.
Therefore, gross salary and net salary are not the same.
Gross salary represents earnings before deductions, while net salary represents the amount payable to the employee after applicable deductions.
What Is the Difference Between CTC, Gross Salary, and Net Salary?
| Salary Term | Meaning |
| CTC | Total annual cost an employer spends on an employee, including salary, employer contributions, and benefits. |
| Gross Salary | Total salary earned before employee-side deductions such as PF, TDS, and Professional Tax. |
| Net Salary | The actual amount credited to the employee’s bank account after applicable deductions. |
What Are the Statutory Payroll Deductions in India?
Statutory payroll deductions are amounts that employers are required to deduct, contribute, deposit, or report when the relevant law applies.
The major payroll-related statutory components include PF, ESI, Professional Tax, and salary TDS.
1. Provident Fund (PF)
Employees’ Provident Fund is a major component of India’s social-security framework.
Under the standard EPF contribution structure, the employee contribution is generally 12%, while the employer’s contribution is allocated between EPF/EPS and other applicable components according to the applicable rules. EPFO’s published contribution table provides the standard rates and notes specific exceptions.
Payroll teams should calculate PF based on applicable wage definitions, contribution rules, eligibility, and establishment-specific circumstances.
2. Employees’ State Insurance (ESI)
ESI provides social security benefits to eligible employees covered under the scheme.
The current contribution rate published by ESIC is generally:
- Employee contribution: 0.75%
- Employer contribution: 3.25%
ESIC also specifies circumstances in which the employee contribution does not apply, such as the prescribed daily average wage exemption.
Employers should verify eligibility and wage limits under the applicable ESI rules rather than applying ESI automatically to every employee.
3. Professional Tax
Professional Tax is a state-level tax applicable in states and Union Territories that levy it.
The rate, slab, exemption, registration requirements, payment deadlines, and return requirements can vary by jurisdiction.
Therefore, employers operating in multiple states should maintain state-specific payroll compliance rules instead of applying one Professional Tax calculation to all employees.
4. Tax Deducted at Source (TDS)
Salary TDS is deducted by the employer from taxable salary and deposited with the government as required.
For payroll from April 2026, employers need to account for the transition to the Income Tax Act, 2025. The Income Tax Department states that the new Act consolidates salary TDS under Section 392 and that payroll systems should be updated for new section numbering and reporting requirements.
Because tax calculations can change with tax policy and employee circumstances, payroll teams should use the latest applicable tax rules when calculating salary TDS.
What Payroll Records and Documents Should Employers Maintain?
Accurate payroll records help employers demonstrate how salaries were calculated and support statutory compliance, audits, employee queries, and financial reporting.
Common payroll records include:
- Employee master records
- Salary structures
- Attendance records
- Leave records
- Overtime records
- Payroll registers
- Payslips
- Bank salary statements
- PF records
- ESI records
- Professional Tax records
- TDS records
- Investment declarations and supporting documents, where applicable
- Reimbursement records
- Bonus and incentive records
- Full and final settlement records
- Salary revision records
- Payroll approval records
- Statutory payment challans
- Applicable returns and filing acknowledgements
The retention period and exact documentation requirements can vary depending on the applicable law and type of record. Employers should therefore establish a documented payroll record-retention policy.
Payroll Processing Example: From Gross Salary to Net Salary
Consider an employee whose monthly salary earnings are:
| Component | Amount |
| Basic Salary | ₹30,000 |
| HRA | ₹12,000 |
| Special Allowance | ₹8,000 |
| Other Earnings | ₹5,000 |
| Gross Salary | ₹55,000 |
Assume the employee has applicable deductions such as PF, Professional Tax, TDS, or other authorized deductions.
The simplified calculation would be:
Gross Salary = ₹55,000
Then:
Net Salary = ₹55,000 − Applicable Employee Deductions − TDS − Other Authorized Deductions
The final bank-credit amount depends on the employee’s actual statutory applicability, tax position, attendance, salary structure, and other payroll adjustments.
Why Should Employers Use a Payroll Calculation Sheet?
A payroll calculation sheet or payroll software can help payroll teams compare:
Opening Salary Data → Monthly Changes → Earnings → Deductions → Net Pay → Statutory Liability
This creates an audit trail and makes it easier to identify unusual changes before salary is released.
How Is Payroll Processed for New Joiners and Exiting Employees?
Payroll processing for new joiners and exiting employees requires additional attention because their salary may not cover a complete payroll period.
Payroll for New Joiners
For a new employee, HR and payroll teams should collect:
- Employee master information
- Date of joining
- Salary structure
- Bank details
- PAN and tax information
- PF/UAN details, where applicable
- ESI details, where applicable
- Tax declarations
- Attendance information
- Applicable benefits and deductions
If the employee joins during the month, salary may need to be calculated on a prorated basis according to the organization’s payroll policy and applicable wage rules.
Payroll for Exiting Employees
When an employee leaves, payroll should account for:
- Last working date
- Salary payable
- Unpaid leave
- Notice-period adjustments
- Incentives or bonus, where applicable
- Reimbursements
- Recoveries
- Leave encashment, where applicable
- Gratuity, where applicable
- Other contractual or statutory dues
This process is generally called Full and Final Settlement (F&F).
A proper exit payroll process helps ensure that the employee receives the correct final settlement and that the employer records the termination accurately.
How Does Multi-State Payroll Processing Work in India?
Multi-state payroll becomes more complex because different states can have different requirements, particularly for Professional Tax and certain employment-related compliances.
For example, an employer with employees working in Maharashtra, Karnataka, Gujarat, Tamil Nadu, and West Bengal may need to maintain separate state-specific payroll rules.
A multi-state payroll process should therefore consider:
- Employee work location
- Establishment registration
- State-specific Professional Tax
- Local wage requirements
- Applicable labour welfare requirements
- State-specific payroll deductions
- Applicable holidays
- Local statutory filings
- Location-specific employee benefits
Best Practice for Multi-State Payroll
Maintain a state-wise payroll compliance matrix containing:
| Compliance Area | State A | State B | State C |
| Professional Tax | Applicable rules | Applicable rules | Applicable rules |
| Labour Welfare Fund | Check applicability | Check applicability | Check applicability |
| Minimum Wage | Applicable rate | Applicable rate | Applicable rate |
| Payroll Filing | Required filing | Required filing | Required filing |
| Payment Deadline | Applicable deadline | Applicable deadline | Applicable deadline |
This approach reduces the risk of applying one state’s payroll rules across the entire organization.
What Are the Common Payroll Processing Mistakes to Avoid?
Payroll errors can result from incorrect employee data, outdated rules, manual calculations, missed deadlines, or inadequate review.
Common mistakes include:
1. Incorrect Employee Data
Incorrect bank details, PAN information, salary structures, or joining dates can lead to wrong salary calculations and payment issues. Payroll teams should regularly verify employee records before processing each payroll cycle.
2. Incorrect Attendance or Leave Data
Incorrect attendance, leave, overtime, or Loss of Pay (LOP) records can affect salary calculations. Employers should finalize and verify attendance data before payroll processing to prevent incorrect employee payments.
3. Applying the Wrong Statutory Rules
Using outdated or incorrect PF, ESI, Professional Tax, or TDS rules can create compliance issues. Payroll teams should regularly review applicable regulations, rates, thresholds, and requirements before calculating deductions.
4. Missing Payroll Cut-Off Dates
Missing payroll cut-off dates for attendance, leave, reimbursements, or salary changes can cause last-minute corrections. Organizations should establish clear deadlines and ensure all payroll inputs are submitted and approved on time.
5. Incorrect TDS Calculation
Incorrect TDS calculations can result in under-deduction, over-deduction, or employee tax discrepancies. Payroll teams should consider applicable tax rules, taxable salary, employee declarations, and the relevant financial year.
6. Ignoring State-Specific Requirements
Payroll requirements can differ across Indian states, particularly for Professional Tax and certain local compliances. Employers operating across multiple locations should maintain state-specific rules to ensure accurate and compliant payroll processing.
7. Not Reconciling Payroll
Payroll should be reconciled with bank payments, accounting records, statutory liabilities, and payroll reports before closing the cycle. Regular reconciliation helps identify calculation differences, duplicate payments, and missing deductions early.
What Happens If Payroll Compliance Deadlines Are Missed?
Missing payroll compliance deadlines can lead to financial and operational consequences.
Depending on the applicable law and nature of the default, consequences may include:
- Interest
- Late fees
- Penalties
- Additional compliance requirements
- Notices from authorities
- Correction filings
- Reconciliation issues
- Employee complaints
- Audit complications
For example, the Income Tax Department states that delayed TDS deposits can attract interest. It also confirms that the general TDS deposit timelines continue under the new tax framework through the applicable rules.
Therefore, employers should maintain a payroll compliance calendar covering:
- Salary processing date
- Salary payment date
- PF payment
- ESI payment
- Professional Tax payment
- TDS payment
- TDS returns
- Applicable state filings
- Other statutory returns
How Can Employers Avoid Missed Payroll Deadlines?
A simple approach is to assign:
Compliance → Owner → Due Date → Status → Payment/Return Reference → Reconciliation
Payroll software can further automate reminders and help maintain a centralized compliance workflow.
How Can Payroll Software Simplify Payroll Processing in India?
Payroll software can automate many repetitive activities involved in payroll processing in India.
Instead of manually moving information between attendance sheets, salary spreadsheets, deduction calculations, and payslips, an integrated payroll system can connect these processes.
Key Benefits of Payroll Software
1. Automated Salary Calculation
Payroll software can calculate salary based on predefined salary structures, attendance, leave, LOP, overtime, incentives, and other inputs.
2. Attendance and Leave Integration
When attendance and leave data are integrated with payroll, salary calculations can be based on approved payroll inputs.
3. Automated Statutory Calculations
Payroll systems can help calculate applicable PF, ESI, Professional Tax, and TDS based on configured rules.
4. Payslip Generation
Employees can receive digitally generated payslips without requiring HR teams to create them manually.
5. Employee Self-Service
Employees can access payslips, salary information, tax-related information, and other HR documents through an employee self-service portal.
6. Compliance Management
A centralized payroll system can help HR teams track payroll compliance requirements and maintain relevant records.
7. Payroll Reports
Organizations can generate reports for:
- Salary costs
- Department-wise payroll
- Location-wise payroll
- Statutory deductions
- Tax deductions
- Attendance
- Leave
- Payroll reconciliation
8. Reduced Manual Errors
Automation reduces repetitive data entry and helps create standardized payroll calculations.
For businesses managing payroll across multiple locations or a growing employee base, payroll automation can make the payroll process more scalable and easier to control.
Payroll Processing Checklist for Indian Employers
Use this checklist before finalizing each payroll cycle.
1. Employee Data
- Employee master data updated
- New joiners added
- Exiting employees identified
- Salary revisions updated
- Bank details verified
- Tax information updated
2. Attendance and Leave
- Attendance finalized
- Leave records approved
- LOP calculated
- Overtime verified
- Shift-related adjustments checked
3. Earnings
- Basic salary verified
- HRA verified
- Allowances checked
- Incentives calculated
- Bonuses processed
- Overtime calculated
- Reimbursements reviewed
4. Deductions
- PF calculated
- ESI checked
- Professional Tax calculated where applicable
- TDS calculated
- Loans and advances adjusted
- Other authorized deductions reviewed
5. Payroll Approval
- Payroll variance reviewed
- Total payroll checked
- Employee count reconciled
- Bank payment file verified
- Payroll approved by authorized personnel
6. Post-Payroll
- Salaries disbursed
- Payslips generated
- Statutory payments completed
- Applicable returns filed
- Payroll reconciled with accounting
- Payroll records archived securely
Conclusion
Payroll processing in India involves much more than calculating monthly salaries. Employers must coordinate employee data, attendance, earnings, deductions, statutory contributions, TDS, salary payments, payslips, compliance filings, and payroll records through a structured process.
A standardized payroll workflow helps organizations reduce errors, improve salary accuracy, maintain compliance, and provide employees with greater transparency. As businesses grow, integrating payroll with attendance, leave, employee management, and HR processes can make payroll faster and easier to manage.
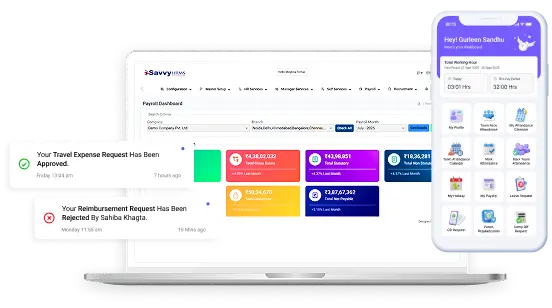


Simplify payroll processing in India with Savvy HRMS, automate salary calculations, compliance, payslips, attendance, and employee payroll management in one integrated platform.
Frequently Asked Questions (FAQs)
1. What is payroll processing in India?
Payroll processing in India is the process of calculating employee salaries, deductions, taxes, statutory contributions, net pay, and completing salary disbursement and applicable compliance activities.
2. What are the main steps in payroll processing?
The main steps include collecting employee data, finalizing attendance and leave, calculating earnings, applying deductions, calculating TDS, determining net salary, approving payroll, and processing payments.
3. What are the common statutory deductions in payroll?
Common statutory payroll deductions include Provident Fund (PF), Employees’ State Insurance (ESI), Professional Tax, and Tax Deducted at Source (TDS), wherever applicable.
4. How is net salary calculated in India?
Net salary is generally calculated by subtracting applicable employee deductions, TDS, Loss of Pay, and other authorized deductions from the employee’s gross earnings.
5. How can payroll software help employers?
Payroll software can automate salary calculations, attendance and leave integration, statutory deductions, TDS calculations, payslip generation, payroll reports, and compliance-related processes, reducing manual work and payroll errors.